


Personal Accident Insurance: A Smart Add‑On to Your Health Insurance Policy
The right features depend on your circumstances and the policy you are considering

A health insurance policy is primarily there to address eligible healthcare expenses when you need medical treatment. But financial pressure after an accident can extend beyond the cost of hospitalisation. If an injury leads to a disability or temporarily affects your ability to work, you may have other expenses to manage at the same time. Personal accident insurance addresses specified accidental events through benefits that may apply to accidental death, disability, or other covered situations, depending on the policy terms.
What Financial Risks Can Follow a Serious Accident?
The immediate concern after an accident is usually treatment. The financial effect, however, can continue after you leave the hospital.
If an injury affects your ability to work, your regular income may be affected while household expenses continue. A serious disability may also require changes to your daily routine or create additional costs. These circumstances are different from the medical expenses that your health policy may cover.
A personal accident policy may provide specified benefits for accidental death or disabilities resulting from an accident.
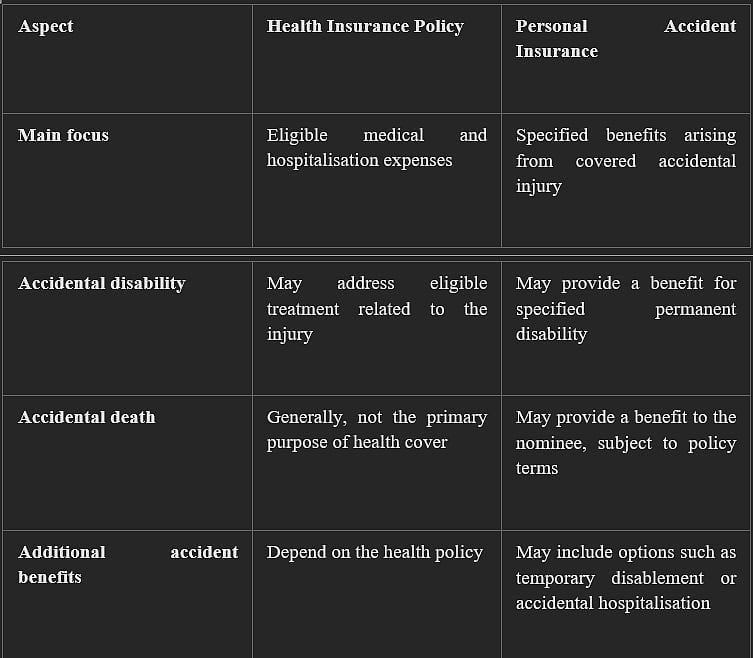
How Can Personal Accident Insurance Complement Health Insurance?
The two types of cover can address different situations.
Which Personal Accident Benefits Should You Look For?
The right features depend on your circumstances and the policy you are considering. When comparing the available cover, check whether it includes benefits such as:
● Accidental death: A specified amount may be payable to the nominee when an accidental death meets the policy conditions.
● Permanent total disablement: A benefit may apply when an accident causes a qualifying permanent and total disability.
● Permanent partial disablement: Some policies provide a defined percentage of the sum insured for specified permanent partial disabilities.
● Temporary total disablement: Certain policies may provide periodic payments when a covered accident temporarily prevents you from working.
● Accidental hospitalisation: This may be available as an optional benefit under some policies, with applicable limits and conditions.
These features are not automatically included in every personal accident policy. Check the policy wording to understand the applicable definitions, limits, conditions, and exclusions.
Conclusion
Your health insurance policy and personal accident insurance can serve different purposes. Reviewing them together can help you identify whether your existing medical cover addresses treatment costs while a separate accident policy addresses specified financial consequences of accidental death or disability. The important step is to assess the actual benefits and conditions rather than assuming that one type of insurance covers every consequence of an accident.
This is an advertorial. The article is published as received.
Join our official telegram channel (@nationalherald) and stay updated with the latest headlines